 By Meghna Sharma
The words tax-free maturity can make an insurance savings plan sound especially attractive. But the tax treatment of a payout is not determined by its product name, the insurer’s brochure or the fact that premiums were paid for many years.
Under Indian income tax law, two life insurance policies with similar maturity values can receive different tax treatment. One may qualify for exemption, while another may produce taxable income because of its premium amount, issue date or relationship between the premium and sum assured.
The key provision is Section 10(10D) of the Income-tax Act, 1961, which governs exemptions for eligible life insurance proceeds.
For policyholders planning to receive maturity benefits in 2026, understanding these conditions is particularly important. Recent changes have restricted exemptions for certain high-premium traditional life insurance policies and unit-linked insurance plans (ULIPs).
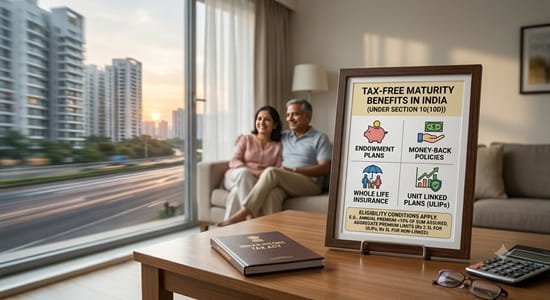
The Basic Rule Behind Tax-Free Insurance Maturity
Section 10(10D) provides an exemption for qualifying sums received under life insurance policies, including eligible bonuses.
However, the exemption is subject to several conditions and exceptions.
For most life insurance policies issued on or after 1 April 2012, the annual premium payable must not exceed 10% of the actual capital sum assured.
For certain policies covering persons with specified disabilities or diseases and issued on or after 1 April 2013, a 15% threshold may apply.
Policies issued between 1 April 2003 and 31 March 2012 generally follow a 20% premium-to-sum-assured threshold.
These conditions are important because a policy’s maturity benefit is not automatically exempt simply because it is described as life insurance.
Traditional Endowment Policies: Tax-Free Only When Eligible
Endowment insurance combines life cover with a maturity benefit payable when the insured survives the policy term.
Many traditional endowment policies can qualify for tax-free maturity proceeds under Section 10(10D).
However, the premium-to-sum-assured condition must be satisfied.
For non-ULIP policies issued on or after 1 April 2023, an additional premium-based restriction applies.
If the annual premium exceeds ₹5 lakh, the maturity proceeds generally do not qualify for the Section 10(10D) exemption, subject to applicable exceptions.
Where multiple relevant policies are involved, aggregate premium rules can also affect eligibility.
Consequently, buying several smaller policies does not necessarily avoid the restriction.
Money-Back Plans and Guaranteed Savings Policies
Money-back policies provide periodic survival benefits during the policy term.
Guaranteed savings plans may provide maturity amounts, income benefits or other contractual payouts.
Both categories can qualify for tax exemption when they meet the relevant Section 10(10D) conditions.
However, their guaranteed benefit structures do not independently determine tax treatment.
For policies issued from 1 April 2023, the ₹5 lakh annual premium restriction for applicable non-ULIP life insurance policies becomes particularly relevant.
A plan marketed as offering guaranteed income may therefore generate taxable proceeds even when the insurer guarantees the payment itself.
A guaranteed payout and a tax-free payout are two different promises.
ULIPs: The ₹2.5 Lakh Premium Limit
Unit-linked insurance plans combine life insurance protection with market-linked investment.
For ULIPs issued on or after 1 February 2021, maturity proceeds generally lose the Section 10(10D) exemption if the annual premium payable exceeds ₹2.5 lakh.
The restriction also considers aggregate premiums across multiple applicable ULIPs.
ULIPs issued before 1 February 2021 are not subject to this particular ₹2.5 lakh restriction, although other exemption conditions still apply.
Where a ULIP’s proceeds are not exempt, the taxable gains are generally assessed under capital gains provisions.
Which Insurance Payouts Remain Exempt?
The following comparison highlights the principal distinctions.
| Insurance policy | Tax-free maturity eligibility |
| Traditional endowment | Yes, if applicable conditions are satisfied |
| Money-back policy | Eligible survival and maturity benefits may qualify |
| Guaranteed savings plan | Depends on premium limits and policy conditions |
| ULIP issued before 1 February 2021 | May qualify under applicable rules |
| ULIP issued from 1 February 2021 | Subject to the ₹2.5 lakh premium restriction |
| Non-ULIP life policy issued from 1 April 2023 | Subject to the ₹5 lakh premium restriction |
| Pure term insurance | Normally has no survival maturity payout |
| Keyman insurance | Excluded from Section 10(10D) exemption |
An important exception concerns death benefits. The premium-based restrictions discussed above generally do not apply to sums received on the insured person’s death. Other specific statutory exclusions remain relevant.
What Happens When Maturity Proceeds Are Taxable?
Losing the Section 10(10D) exemption does not necessarily mean the entire maturity amount becomes taxable income.
For taxable non-ULIP life insurance proceeds, the applicable computation generally accounts for qualifying premiums paid that have not already been claimed as deductions elsewhere.
The resulting income is generally taxable under Income from Other Sources.
For taxable ULIPs, capital gains provisions apply.
The actual liability depends on the policy, payment history and applicable tax rules.
Five Details to Check Before Maturity
Before assuming an insurance payout will be exempt, examine:
- Issue date: Determines which premium restrictions apply.
- Policy category: ULIPs and non-ULIP policies have different monetary thresholds.
- Annual premium: Must satisfy the applicable limits.
- Sum assured: Relevant to the premium-to-sum-assured condition.
- Other policies: Aggregate premium rules may affect exemption eligibility.
Also remember that a deduction claimed on premiums under Section 80C and an exemption on maturity proceeds under Section 10(10D) are separate tax benefits. Eligibility for one does not guarantee the other.
Frequently Asked Questions
Q1. Are LIC maturity benefits completely tax-free?
A: Not automatically. LIC maturity proceeds qualify for exemption only when the relevant policy satisfies Section 10(10D) conditions. The insurer’s identity does not independently guarantee exemption.
Q2. Is the maturity amount of an endowment policy taxable?
A: It may be tax-free if the applicable premium-to-sum-assured and monetary premium restrictions are satisfied. Otherwise, the taxable income is calculated under the relevant provisions.
Q3. What is the ₹5 lakh insurance premium rule?
A: For applicable non-ULIP life insurance policies issued on or after 1 April 2023, maturity exemption is generally unavailable where annual premiums exceed ₹5 lakh. Aggregate premium rules also apply to multiple relevant policies.
Q4. Are ULIP maturity benefits tax-free after five years?
A: Not necessarily. Completing the five-year lock-in period does not independently establish tax exemption. The issue date, premium limits and other Section 10(10D) conditions determine eligibility.
Q5. Are life insurance death benefits taxable in India?
A: Death benefits are generally exempt under Section 10(10D), even where the high-premium maturity restrictions would otherwise apply. Specific statutory exceptions must still be considered.
For anyone expecting a substantial insurance payout, the most useful step is to obtain the policy’s tax treatment details before maturity. A written assessment based on the actual contract and premium history is more reliable than a general claim that life insurance maturity benefits are always tax-free.